Chapter 12 answered one question completely: an
operator has an orthonormal basis of eigenvectors
exactly when it is normal. That answer is useless for a
matrix,
which has no eigenvalues at all — the equation is not even type-correct,
because
and live
in different spaces. This section shows that every
matrix, of every shape, still admits an
orthonormal-to-orthogonal description, and that the
numbers in it are the eigenvalues of a positive
semidefinite matrix we already understand. It is the
most-used factorization in applied linear algebra, and
the whole of it comes from applying the spectral theorem
to .
Throughout, is
or , is the conjugate
transpose (the transpose when ), and
unitary means unitary over and orthogonal over
, as in Definition 11.7.2.
Both and carry their standard
inner products.
Where to
look when there are no eigenvalues
Let . There is exactly one square matrix that
can be built from at no cost, and
Chapter 11 has already used it twice: the matrix of the normal
equations. It is self-adjoint, since , and it is positive semidefinite for
the reason that makes every argument in this chapter
work:
(13.9.1)
So , and Theorem 13.1.4 says
its eigenvalues are nonnegative real numbers, while the
spectral theorem supplies an orthonormal basis of consisting of its
eigenvectors. Those eigenvalues are attached to , they exist for every
shape of , and Eq. 13.9.1 says what
they measure: how much stretches.
A rectangular matrix has no eigenvalues of its
own, but
does, and their square roots are the stretching factors
of .
Definition
13.9.1 (Singular Values)
Let and put . Let be the eigenvalues of ,
listed with multiplicity in decreasing
order. The singular values of are so that . We write when is clear.
Clause by clause. The list has exactly entries,
not : when the matrix has rank by
Corollary 11.6.6
(b), so and the discarded
eigenvalues are all zero. The square root is the
ordinary nonnegative real square root, available because
every . The ordering is decreasing,
matching the book’s convention for the eigenvalues of a
Hermitian matrix, and it is part of the definition: “the
second singular value” means a definite number. Finally,
the singular values are attached to itself, with no
choices made, because the eigenvalue list of is.
Four examples, simplest first.
- The identity. gives , so every
. More
generally a unitary has , so all its singular values are . A unitary matrix
stretches nothing in any direction, and the list of
singular values says exactly that.
- A rectangular diagonal matrix. If
has for and all other entries , then and the singular values are
sorted
downwards. The absolute value matters: the
singular values of are .
- A positive semidefinite matrix. If
then
,
whose eigenvalues are with
, so . For the matrices this chapter
started with, singular values and eigenvalues
coincide.
- A single row. For with , and , whose nonzero eigenvalue
is . So
. The degenerate case has every , and it
matters: it is the only matrix with , since forces and then
for every by Eq. 13.9.1.
Now the nonexample, by minimal change. Replace
“square roots of the eigenvalues of ” by “absolute
values of the eigenvalues of ”. For , and more
generally for any normal , the two agree (Exercise (C3: Singular values equal to eigenvalue moduli)).
But the second recipe is undefined for a nonsquare
matrix, and for it returns , while gives the singular values . The clause that
fails is the one that does all the work: is positive
semidefinite for every , whereas itself may have no
useful spectrum.
Warning. Singular values
are not eigenvalues. The matrix above has both
eigenvalues equal to and largest singular
value : it
annihilates but sends
to a
unit vector, so calling it “small” because its spectrum
is is wrong.
Singular values are always real and nonnegative;
eigenvalues need not be either. The two lists agree,
after taking absolute values, exactly for normal
matrices — this is Exercise (C3: Singular values equal to eigenvalue moduli),
and Chapter 12’s Schur inequality is what makes the
converse true.
Quick check. What are the singular
values of an orthogonal projection onto an
-dimensional
subspace?
Solution. ,
because an orthogonal projection is self-adjoint and
idempotent. So the eigenvalues of are those of
, namely with multiplicity and with multiplicity . Sorted downwards,
the singular values are and . This is also Example 3
above, since .
The
theorem
Here is the payoff. The eigenvectors of are an
orthonormal basis of the domain; the claim is that carries them to an
orthogonal list in the codomain, whose
lengths are the singular values.
Theorem
13.9.1 (Singular Value Decomposition)
Let , let , and let be its singular values. Then there are
unitary matrices and such that where has
for
and every other entry . Moreover the number of
nonzero
equals .
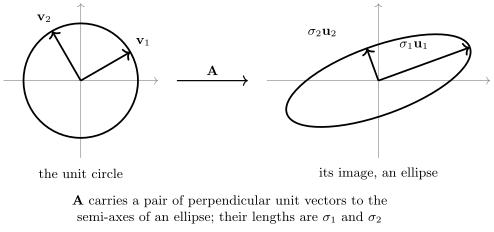
Idea. Picture the real case. A
matrix carries the unit circle to an ellipse, and an
ellipse has two perpendicular axes; the theorem says
that the two unit vectors sent to the ends of those axes
are themselves perpendicular. That is exactly what
Chapter 12’s principal axis theorem (Theorem 12.5.5)
said about the level curves of a quadratic form, and the
link is that
is a quadratic form, with matrix . So the plan is:
① diagonalize by the spectral
theorem, getting an orthonormal basis with ; ② compute
and watch the eigenvalue equation force it to be , so
the images are already orthogonal; ③ normalize the
nonzero ones to unit vectors , and, if there
are fewer than of
them, pad the list out to an orthonormal basis of ; ④ read off
column by column.
Proof. Step 1: diagonalize
.
The matrix is self-adjoint, and Eq. 13.9.1 makes it
positive semidefinite in the sense of Definition 13.1.1. By
the spectral theorem in matrix form — Corollary 12.5.2
when , Corollary 12.4.3
when , each
of which allows the eigenvalues to be listed in a
prescribed order — there is a unitary with
columns such that the eigenvalues being nonnegative by Theorem 13.1.4. Set
for all ; for these are the
singular values of Definition 13.9.1.
Step 2: the images are orthogonal.
For all , using
and the eigenvalue
equation, the first equality by Definition 11.6.1
and the last because is unitary, so its
columns are orthonormal (Theorem 11.7.3
(f)). In particular , so
Step 3: normalize, and count. Let
be the number of
indices with ; since the decrease, these
are . For put which is legitimate because . By Step
2, for , so is an orthonormal list in .
We claim . Any is since is a basis, and then by Eq. 13.9.2. Hence
, and the are
orthonormal, hence independent (Theorem 11.1.4), so
. In
particular , so every index with satisfies
, and the
nonzero singular values are exactly .
Step 4: pad the list. If the list is already an orthonormal basis of
, and we set
. If , apply Corollary 11.2.3 to
the orthonormal list in : there are making an orthonormal basis of . Either way let have these
columns; it is unitary because its columns are
orthonormal (Theorem 11.7.3
(f)). Note that the padding vectors are
not determined by , and nothing below
uses any property of them beyond orthonormality.
Step 5: read off the columns. Let
be as in the statement. Column of is times column of , which is for
and for ; so column of is for
and for . Column of is .
Compare:
- for ,
by the definition of ;
- for , , so both columns are by Eq. 13.9.2;
- for
(possible only when ), we have , so and ,
and both columns are .
Hence . Since is unitary, , so
. This proves the theorem.
A factorization as in the theorem is called
a singular value decomposition of , the columns of are left
singular vectors and the columns of are right
singular vectors. The two equations to keep in
mind are the ones the proof produced,
(13.9.3)
the second obtained by applying to the first and
using . In words: matches up two
orthonormal bases, one in each space, stretching the
-th direction by
, and runs the same
correspondence backwards with the same factors.
Here is the picture the Idea described, in the real
case.
Compare the principal axes figure of Chapter 12 §05.
There the ellipse was a level curve
of a quadratic form and the axes lay along the
eigenvectors of a symmetric ; here the ellipse is
the image of the unit circle under an arbitrary
. The two
pictures are the same picture, because is a quadratic
form with matrix , and the right
singular vectors of are its principal
axes. A large now means a
long semi-axis, whereas in Theorem 12.5.5 a
large
meant a short one; the reason is that the two pictures
are related by taking reciprocals of square roots.
What is
unique and what is not
The singular values were defined before the theorem,
so they cannot depend on any choice. What needs saying
is the converse: any factorization of the stated shape
recovers them.
Theorem
13.9.2 (The Singular Values Are
Determined)
Let and suppose with
unitary and
of the shape in Theorem 13.9.1, with
diagonal entries . Then for
every .
Moreover:
- (a) the columns of
are forced to be
an orthonormal basis of consisting of
eigenvectors of , with for every , where for
; and
any such basis occurs;
- (b) once is chosen, is forced for every , while
may be any orthonormal basis of
.
Proof. From and
,
and is the diagonal matrix with entries
followed by zeros. So is unitarily
diagonalized with this diagonal, and its eigenvalue list
in decreasing order is therefore — already sorted, since the are. Comparing with
Definition 13.9.1
gives , hence
because both are nonnegative.
(a) The displayed
equation says the -th column of satisfies , and the columns of a
unitary matrix are orthonormal. Conversely, given any
orthonormal basis of eigenvectors of ordered by
decreasing eigenvalue, Steps 2–5 of the proof of Theorem 13.9.1 build a
factorization from it.
(b) For we have , and
comparing column
of
gives , so . For the
corresponding column of is zero, so is
unconstrained by the equation ; the
only constraint left is that be orthonormal, which says exactly
that is an orthonormal basis of .
So is
unique and
are not. The freedom is of two kinds, and both are
visible in small cases. If has a repeated
eigenvalue, any orthonormal basis of that eigenspace may
be used:
has
and for every unitary
, with . If the
eigenvalues are distinct, each is still free
up to a scalar of modulus , and replacing by replaces
by , leaving
unchanged because .
Steps 3 and 5 of the proof produced more than the
statement recorded: they located and inside the two
bases. Writing the factorization so that only the
nonzero singular values appear makes this visible.
Theorem
13.9.3 (Compact Singular Value
Decomposition)
Let have rank and let be
as in Theorem 13.9.1, with
columns and . Then a sum of matrices of rank . Equivalently , where and hold the first columns of and , and is square and
invertible.
Proof. Write .
The columns of are followed by zero columns, as
computed in Step 5 of Theorem 13.9.1, and
the rows of
are . By the outer product expansion
of a matrix product (Corollary 8.1.3),
the terms with vanishing because there. Each
is nonzero with all columns multiples of , hence of rank
. The same
computation with the truncated matrices gives , and
is
invertible because its diagonal entries
are nonzero.
Corollary
13.9.4 (The Four Fundamental Subspaces from the
Compact Form)
With the notation of Theorem 13.9.3:
- (a) is an orthonormal basis of ;
- (b) is an orthonormal basis of ;
- (c) is an orthonormal basis of ;
- (d) is an orthonormal basis of .
Idea. Two of the four were proved
on the way to Theorem 13.9.1. The
other two come for free by applying the same statements
to , whose
singular value decomposition is — the roles of and simply swap.
Proof. Part (a). Step 3 of
Theorem 13.9.1 showed
, and these vectors are
orthonormal.
Part (d). By Eq. 13.9.2,
exactly for , and for we computed . Since the are
independent and the nonzero for
, if
and only if , that is, .
Parts (b) and (c). Taking conjugate
transposes, , and has the same diagonal . So this is a singular value
decomposition of , with the columns
of as left
singular vectors and those of as right singular
vectors, and by Corollary 11.6.6
(a). Now the two parts just proved, applied to instead of , give exactly (c) and
(b).
This is the cleanest possible form of Theorem 11.6.5.
That theorem said the four subspaces come in two
orthogonal pairs, and . The corollary hands over
orthonormal bases of all four at once,
out of two matrices, and adds the missing piece of
information: how
maps one pair to the other. Restricted to , the map is a bijection onto
, and in the
bases and its matrix is the diagonal . Every matrix,
after an orthonormal change of basis on each side, is a
positive diagonal matrix padded with zeros.
Quick check. Let
have rank . Using
Corollary 13.9.4, what
is ,
and why does the answer not depend on which singular
value decomposition was used?
Solution. The list has members, so .
It cannot depend on the factorization because is determined
by (Theorem 13.9.2), and
in any case the answer agrees with from Theorem 11.6.5 and
Theorem 11.3.2.
Two
computations and one comparison
The Frobenius norm. From and , or directly from
Lemma 11.7.5, So the Frobenius norm is the Euclidean length
of the singular value list. Section 11 turns this one
identity into the best low-rank approximation
theorem.
The largest stretch. Let be a unit vector, so by Theorem 11.9.2.
Then , and since the
are
orthonormal, Pythagoras (Theorem 11.1.3)
gives with equality at . So
: the largest singular value is the largest
factor by which
can lengthen a vector. Chapter 16 gives that quantity a
name, the operator norm , and this
computation is why .
Against the eigenvalues. For a
normal , write with by Corollary 12.4.3.
Then so the singular values of are the moduli ,
sorted downwards. For a general matrix there is no
relation at all in one direction — has spectrum and — and only
the crude bound in the other, since with gives
.
Example
(A singular value decomposition of a 2 by 3
matrix)
Find a singular value decomposition of and read off orthonormal bases of its four
fundamental subspaces.
Solution. Here , , . The proof asks for
the eigenvectors of the matrix , but there is a
shortcut worth taking whenever : run the proof
on instead.
It produces , and transposing that
equation gives , which is what we want. The
eigenvalue computation then lives in the smaller matrix
Step 1. The characteristic polynomial of
is , so the eigenvalues are and and the singular values
are , . For , gives , and for we get . Normalizing,
Both singular values are nonzero, so .
Steps 2–4. The roles of and are swapped
along with the roles of and , so here : This time the padding step is needed, since
: a
unit vector orthogonal to both is
Step 5. Assembling, As a check, and .
The four subspaces (Corollary 13.9.4),
with : has the
orthonormal basis ,
which is all of , so ;
has the orthonormal basis ;
and is the line through . The last is
easy to verify directly: .
Exercises
A. Check your
understanding
Exercise
(A1)
- (a) Define the
singular values of a matrix .
How many are there?
- (b) State the
singular value decomposition, with the size and the
defining property of each factor.
- (c) True or false:
the singular values of are the absolute
values of its eigenvalues. Justify your answer.
- (d) How many nonzero
singular values does have, and why?
- (e) Given a compact
singular value decomposition , write down
orthonormal bases of all four fundamental subspaces of
.
- (f) True or false:
in the three factors are
determined by .
Justify your answer.
Solution.
(a) They are
for ,
where are the eigenvalues of
with
multiplicity (Definition 13.9.1).
There are of them.
(b) Theorem 13.9.1: with
unitary, unitary, and having in positions and zeros
elsewhere.
(c) False. has both eigenvalues
and singular
values . The
statement is true for normal matrices (Exercise (C3: Singular values equal to eigenvalue moduli)),
and for a nonsquare matrix it does not even make
sense.
(d) Exactly , by Theorem 13.9.1. The
reason is that precisely when , so the
with
span
.
(e) for ; for ; for ; for (Corollary 13.9.4).
(f) False for
and , true for (Theorem 13.9.2). For
instance for every unitary . The freedom is: any
orthonormal eigenbasis of may be used for
, and the last
columns of
may be any
orthonormal basis of .
B. Practice
Exercise
(B1: A 2 by 2 decomposition)
Find a singular value decomposition of
and compare the singular values with the
eigenvalues of .
Solution. , with
characteristic polynomial , whose roots are and . So and
.
For
the equation gives ; for , . Then Hence and . Check: .
The eigenvalues of are and , the diagonal entries
of a triangular matrix. They are not the singular
values, not even after reordering: is not normal, since
. Note, however, that , as Exercise (C2: The adjoint and the determinant)
explains.
Exercise
(B2: When the left singular vectors must be
padded)
Find a singular value decomposition of saying explicitly where the padding step of Theorem 13.9.1 is
used.
Solution. ,
already diagonal with decreasing diagonal, so , ,
, and , . Both are
nonzero, so .
Then Here , so Step 4 of Theorem 13.9.1
applies: extend to an orthonormal basis of . A vector
orthogonal to both is , so take . Then and . The vector is not
determined by
beyond its line: would do just
as well. By Corollary 13.9.4,
, which is confirmed by .
Exercise
(B3: Compact form and the four subspaces)
For find the compact singular value decomposition
, and hence
orthonormal bases of all four fundamental subspaces.
Solution. , with eigenvalues
and , so , , and . An eigenvector for
is , and for it is . Then a unit vector since . The
compact form is , and
multiplying out gives back .
Four subspaces: and , both
one-dimensional; ; and
is the
plane , for which an orthonormal
basis is
and .
(Any orthonormal basis of that plane is a legitimate
, which is the freedom described in
Theorem 13.9.2
(b).)
Exercise
(B4: Determine whether)
Determine which of the following statements are
correct. For those that are correct, prove them; for
those that are not, give a counterexample.
- (a) If every
eigenvalue of is , then every singular
value of is
.
- (b) for every scalar .
- (c) for every square .
- (d) is invertible if and
only if and
every singular value of is nonzero.
Solution.
(a) Incorrect.
has spectrum , while
gives .
(b) Correct.
,
whose eigenvalues are ; taking square roots and
noting that multiplying by
preserves the decreasing order gives the claim.
(c) Incorrect,
with the same :
has both
singular values ,
while . (It is correct for , and more
generally for normal , because then the
singular values are the moduli of the eigenvalues and
has
eigenvalues .)
(d) Correct. If
then,
by Theorem 13.9.1, the
number of nonzero singular values is , and is invertible exactly
when
(Theorem 7.5.3 (d)). A
nonsquare matrix is never invertible.
C. Going deeper
Exercise
(C1: The Frobenius norm and the largest singular
value)
Let with singular values .
- (a) The text
obtained from unitary
invariance. Prove it a second way, directly from and the eigenvalues of , without
invoking Lemma 11.7.5.
- (b) Deduce that
, and determine exactly when
equality holds.
Solution.
(a) Take a
singular value decomposition (Theorem 13.9.1). By Lemma 11.7.5,
applied once on each side, .
The only nonzero entries of are
on the diagonal, so .
(b) Every term of
is
nonnegative, so , and
taking nonnegative square roots gives .
Equality holds if and only if , that is, if and only if (Theorem 13.9.1).
Exercise
(C2: The adjoint and the determinant)
Let .
- (a) Prove that and have the same
nonzero singular values, with the same
multiplicities.
- (b) Suppose . Prove that .
- (c) Hence give a
formula for in
terms of
only, and check it on .
Solution.
(a) If is a
singular value decomposition, then with unitary and carrying the same diagonal entries
. By Theorem 13.9.2 this is
a singular value decomposition of , so the singular
value list of is
as well. (The two lists have the same length , so they
are in fact equal, not merely equal in their nonzero
parts.)
(b) Take
determinants in . By Theorem 7.5.4, . A unitary has ,
since and , so .
The same holds for . And by Theorem 7.4.6. Taking
absolute values gives .
(c) Squaring,
, so . For the given , and .
Exercise
(C3: Singular values equal to eigenvalue moduli)
Let have eigenvalues listed with algebraic multiplicity
and ordered so that .
- (a) Prove that if
is normal, then
for every .
- (b) Prove the
converse: if for every , then is normal.
Hint for (b): compare two expressions for .